The 'Buy at Pre-Launch, Sell at Possession' Strategy Deep Dive
This is the single highest-ROI strategy in Indian real estate. We break down the mechanics, the risks, and the numbers that make it work.
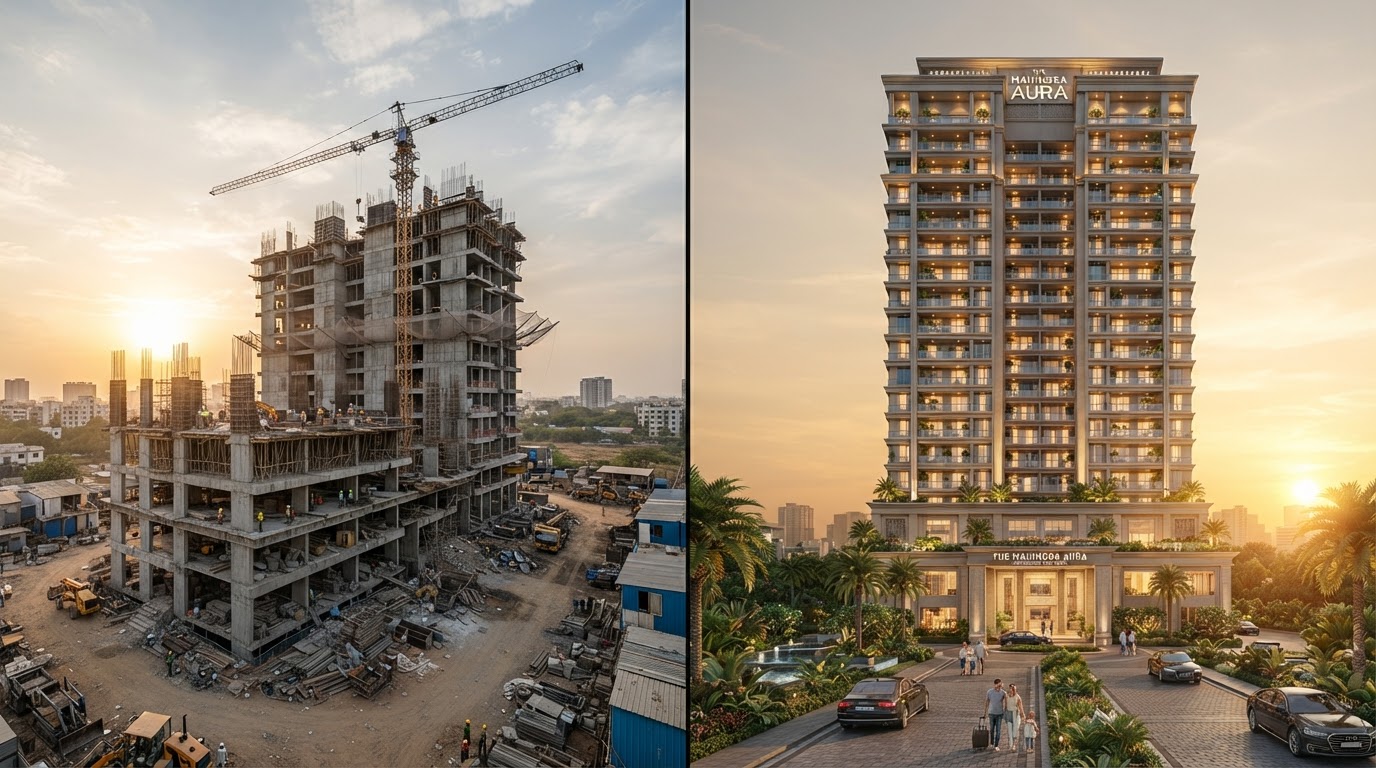
The 'buy at pre-launch, sell at possession' strategy is the single highest-ROI approach in Indian residential real estate. It captures the full construction-phase appreciation — the steepest part of the property's appreciation curve — while minimizing capital outflow through payment plan structuring. Here's the deep dive.
The mechanics:
1. Entry at pre-launch: You book the property at pre-launch pricing, which is typically 15–25% below the launch price. You pay a small booking amount (10–15% under CLP, or 10–25% under subvention).
2. Hold through construction: Over the 3–5 year construction period, the property appreciates as milestones are completed, approvals are received, and the project gains visibility. The pricing steps up in tranches.
3. Exit at possession: When the property receives its OC and possession is offered, the pricing has reached the ready-to-move level — typically 30–50% above the pre-launch rate. You sell to an end-user (who pays a premium for ready-to-move property) and capture the full appreciation.
The numbers:
On a ₹2 Cr property (pre-launch rate ₹8,000/sq ft, ready-to-move rate ₹12,000/sq ft): - Entry: ₹2 Cr at pre-launch, 20% down (₹40 lakh) via subvention. - Construction period (4 years): Zero additional payment (subvention), zero interest. - Exit at possession: Property value = ₹3 Cr (50% appreciation). Pay remaining 80% (₹1.6 Cr) at possession, sell for ₹3 Cr. - Gain: ₹3 Cr - ₹2 Cr = ₹1 Cr. ROI on invested capital (₹40 lakh) = 250% over 4 years = ~50% annualized.
This is the power of the strategy: the appreciation accrues on the full ₹2 Cr property value, while your capital at risk is only ₹40 lakh. The subvention eliminates the interest cost, making the leverage free.
The risks:
1. Timeline risk: If possession is delayed beyond the projected 4 years, your capital is locked longer. The ROI annualized declines, and opportunity cost increases. Mitigation: invest only with tier-1 developers with credible delivery track records.
2. Pricing risk: If the micro-market's appreciation slows, the exit pricing may be lower than projected. Mitigation: select micro-markets with structural demand drivers (IT employment, infrastructure, supply constraint).
3. Liquidity risk: The exit depends on finding a buyer at possession. If the market is slow, the exit may take 6–12 months. Mitigation: select projects with strong end-user demand (not just investor demand), so the buyer pool is wide at possession.
4. Subvention availability: Subvention is not always available, and the window is narrowing. If subvention is not available, use CLP — the ROI is lower (because you pay throughout construction) but still strong.
When the strategy works best:
- Tier-1 developer with credible delivery track record - Emerging micro-market with structural demand drivers - Pre-launch or early under-construction entry - Subvention or CLP payment plan available - 4–5 year hold to possession
Our view: this is the core strategy we position investors for. The combination of pre-launch entry pricing, subvention/CLP payment deferral, and possession-stage exit to end-users is the highest-ROI approach in Indian residential real estate. The key is execution — selecting the right developer, the right micro-market, and the right payment plan. When those three align, the strategy consistently delivers 40–60% appreciation with minimal capital outflow.
Want these insights delivered before anyone else?
Join our confidential investor briefing — subvention alerts, off-market deals and market intelligence, first.
More from Investment Strategy
How Investor Syndication Unlocks Wholesale Developer Pricing
One investor gets retail pricing. Ten investors syndicated through us get wholesale. Here's the mechanics of bulk-buying power.
REITs vs Physical Property: Where Should the Smart Money Go?
Indian REITs offer liquidity and yield, but physical property offers leverage and appreciation. We compare the two.
How Indian Family Offices Are Allocating to Real Estate in 2026
Family offices are shifting from pure equity to real estate for yield, inflation hedge, and generational wealth. We break down the allocation framework.