Construction-Linked Payment Plans (CLP): The Self-Funding Investor's Tool
CLP spreads your payment across construction milestones, reducing upfront outflow and aligning payment with progress. Here's how to use it.
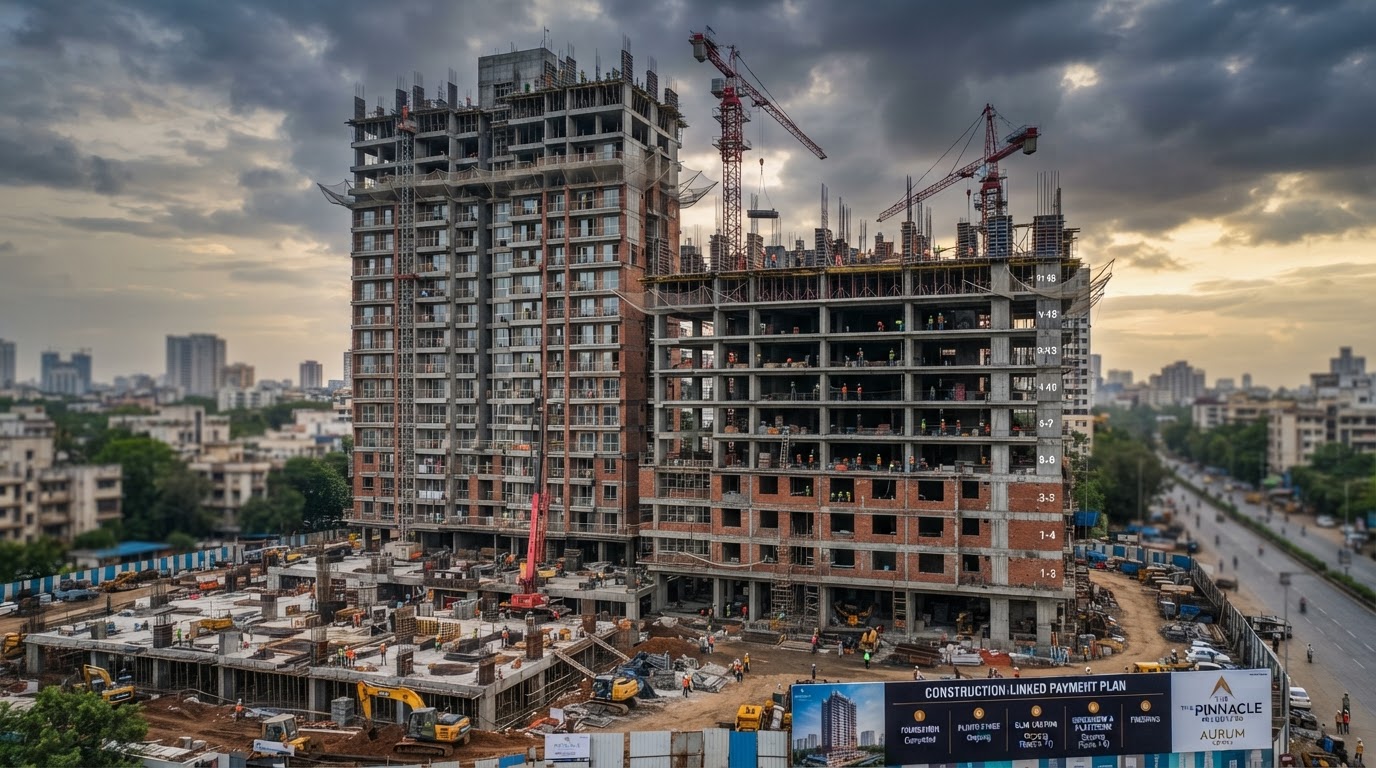
Construction-Linked Payment (CLP) is the most widely used payment plan for under-construction property in India, and it's particularly valuable for self-funding investors who want to spread their capital outflow across the construction period.
How CLP works:
Under a CLP, you pay 10–15% at booking, and the remaining amount is paid in installments tied to construction milestones. A typical 10-milestone CLP schedule looks like this:
1. Booking: 10% 2. Excavation: 10% 3. Foundation: 10% 4. First slab: 10% 5. Third slab: 10% 6. Sixth slab: 10% 7. Ninth slab: 10% 8. Brickwork: 10% 9. Plastering & flooring: 10% 10. Possession: 10%
Each installment is triggered only when the corresponding milestone is completed and certified. This means your payment is aligned with construction progress — you pay as the property is built.
The self-funding advantage:
For investors who are self-funding (not taking a loan), CLP offers two key benefits:
1. Capital efficiency: Instead of paying 90% upfront (as in a down payment plan), you spread the payment across 3–4 years. Your capital remains deployed elsewhere (earning returns) until each milestone payment is due.
2. Risk protection: If construction stalls, your payment stops. You only pay for completed milestones, which means a stalled project doesn't drain your capital. This is a built-in risk filter.
CLP vs subvention for self-funders:
Subvention defers 80% of payment to possession, which is even more capital-efficient. However, subvention is not always available (it depends on the developer and the project stage). CLP is the more universally available option, and it's the default plan for most under-construction projects.
The ROI math:
On a ₹2 Cr property with a 4-year construction period: - Down payment plan (90% upfront): ₹1.8 Cr outflow at booking. Effective cost of capital = the return you could have earned on ₹1.8 Cr over 4 years. - CLP (10% at booking, rest over 4 years): ₹20 lakh outflow at booking, rest spread out. Your average capital deployment is roughly half the total, meaning your effective ROI on invested capital is significantly higher.
Our view: CLP is the default payment plan for self-funding investors. It balances capital efficiency with risk protection, and it's available on virtually every under-construction project. If subvention is available on a tier-1 developer project, take it — but CLP is the reliable fallback that every investor should understand.
Want these insights delivered before anyone else?
Join our confidential investor briefing — subvention alerts, off-market deals and market intelligence, first.
More from Investment Strategy
How Investor Syndication Unlocks Wholesale Developer Pricing
One investor gets retail pricing. Ten investors syndicated through us get wholesale. Here's the mechanics of bulk-buying power.
REITs vs Physical Property: Where Should the Smart Money Go?
Indian REITs offer liquidity and yield, but physical property offers leverage and appreciation. We compare the two.
How Indian Family Offices Are Allocating to Real Estate in 2026
Family offices are shifting from pure equity to real estate for yield, inflation hedge, and generational wealth. We break down the allocation framework.