Holding Period Optimization: 3-Year vs 5-Year vs 7-Year Returns
The holding period determines your tax rate, appreciation capture, and annualized ROI. We compare 3, 5, and 7-year holds with real numbers.
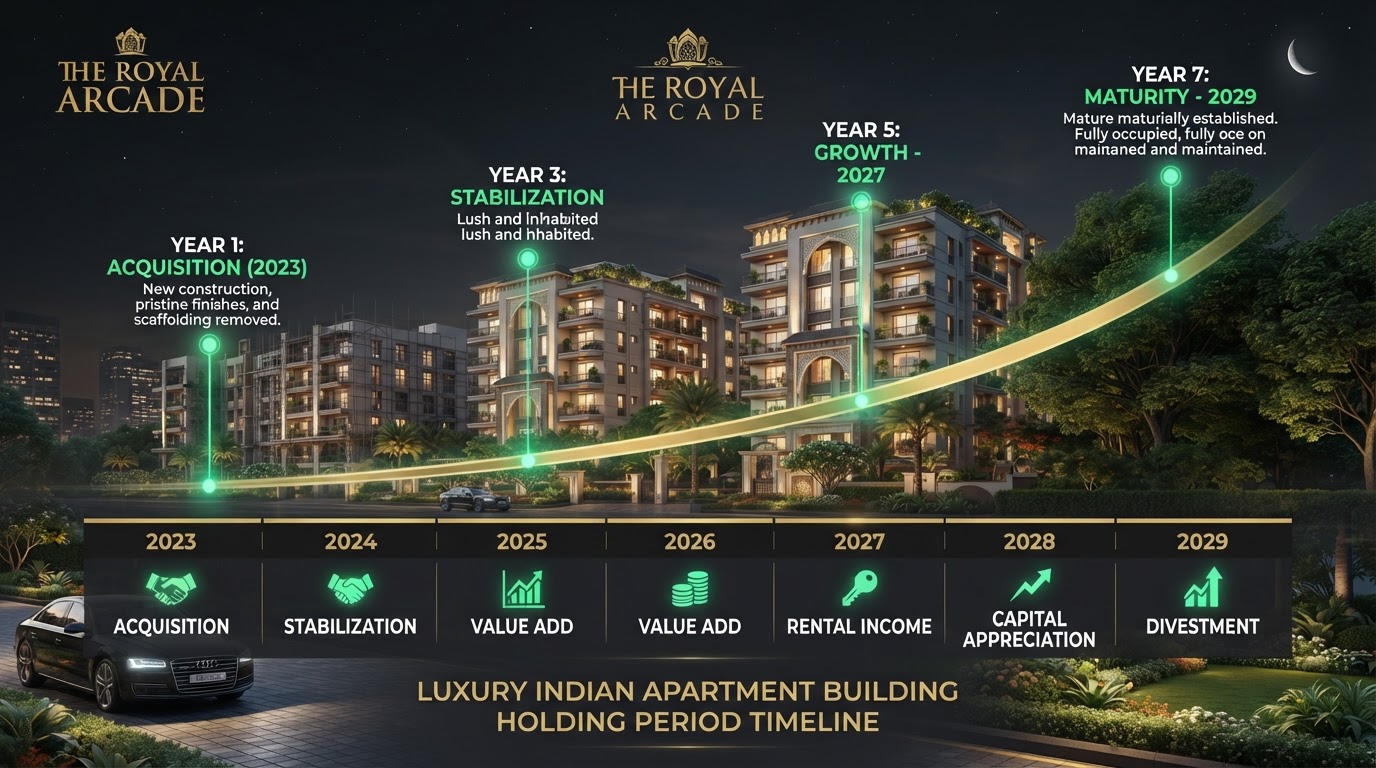
The holding period is a strategic decision that affects your tax rate, your appreciation capture, and your annualized ROI. There's no single 'best' holding period — it depends on your tax bracket, the micro-market's appreciation velocity, and your capital allocation strategy. Here's our comparison of 3, 5, and 7-year holds.
The 3-year hold:
The 3-year hold is the minimum for tax efficiency. Under Indian tax law, property held for more than 24 months qualifies as long-term capital gain (LTCG), taxed at 12.5% (without indexation, post-Budget 2024). Held for less than 24 months, it's short-term (STCG), taxed at your slab rate (up to 30%+).
The 3-year hold captures the steepest part of the appreciation curve — the construction-phase appreciation from pre-launch to possession. For a pre-launch entry, 3 years typically captures 30–40% appreciation.
The disadvantage: the annualized ROI is high, but the absolute return is moderate. And if the construction period is 4–5 years, a 3-year hold means exiting before possession (via assignment), which narrows the buyer pool.
The 5-year hold:
The 5-year hold is the sweet spot for most investors. It captures the full construction-phase appreciation (pre-launch to possession, typically 40–60%) plus 1–2 years of post-possession appreciation and rental income.
The tax treatment is favorable (LTCG at 12.5%), and the exit is at or after possession, when the buyer pool is widest (end-users + investors). The annualized ROI is typically 12–15%, with a strong absolute return.
The 7-year hold:
The 7-year hold captures multiple appreciation cycles and compounds rental income. The total return (appreciation + yield) can be the highest in absolute terms, but the annualized ROI tends to plateau after year 5–6, as the aggressive construction-phase appreciation is over.
The 7-year hold suits investors who want rental income and are not in a hurry to redeploy capital. It's also favorable for tax planning — the longer hold means more time to plan reinvestment under Section 54.
ROI comparison (₹2 Cr pre-launch entry, 12% annual appreciation, 3% rental yield post-possession at year 4): - 3-year hold: 36% appreciation = ₹72 lakh. LTCG tax (12.5%) = ₹9 lakh. Net = ₹63 lakh. Annualized = 12%. - 5-year hold: 54% appreciation + 1 year yield (3% of ₹3.08 Cr) = ₹1.08 Cr + ₹9.2 lakh = ₹1.17 Cr. Tax = ₹14.6 lakh. Net = ₹1.02 Cr. Annualized = ~14%. - 7-year hold: 72% appreciation + 3 years yield = ₹1.44 Cr + ₹31 lakh = ₹1.75 Cr. Tax = ₹21.9 lakh. Net = ₹1.53 Cr. Annualized = ~13.5%.
Our framework: For most investors, the 5-year hold optimizes the balance of annualized ROI, absolute return, and tax efficiency. The 3-year hold is optimal when you need capital liquidity or when the appreciation is exceptional. The 7-year hold is optimal for rental-income-focused investors. The key is to match the holding period to your capital allocation strategy and tax planning.
Want these insights delivered before anyone else?
Join our confidential investor briefing — subvention alerts, off-market deals and market intelligence, first.
More from Investment Strategy
How Investor Syndication Unlocks Wholesale Developer Pricing
One investor gets retail pricing. Ten investors syndicated through us get wholesale. Here's the mechanics of bulk-buying power.
REITs vs Physical Property: Where Should the Smart Money Go?
Indian REITs offer liquidity and yield, but physical property offers leverage and appreciation. We compare the two.
How Indian Family Offices Are Allocating to Real Estate in 2026
Family offices are shifting from pure equity to real estate for yield, inflation hedge, and generational wealth. We break down the allocation framework.