Home Loan Pre-Approval: Does It Strengthen Your Negotiation?
A pre-approved loan signals you're a serious, qualified buyer. We explain how it strengthens your hand in developer negotiations.
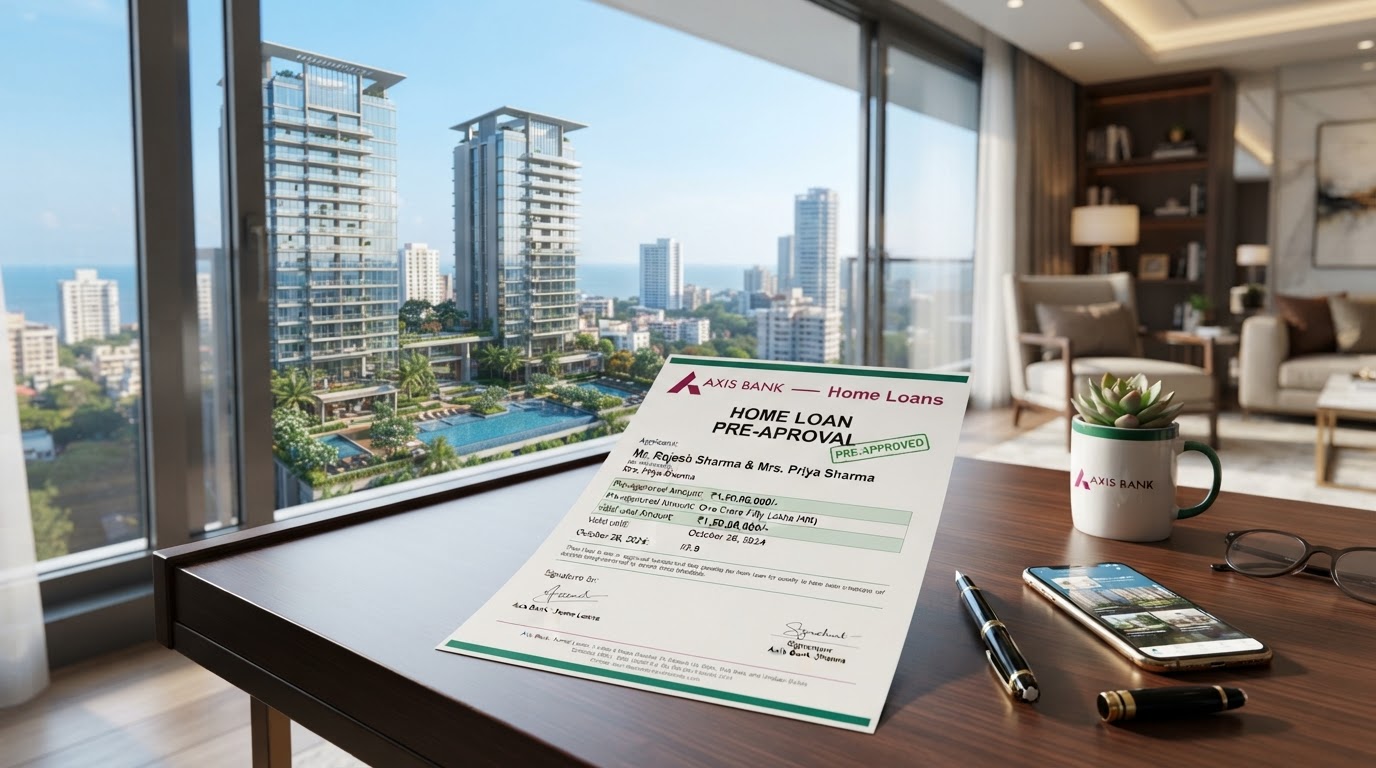
A home loan pre-approval is a conditional sanction letter from a bank or housing finance company, stating the loan amount you're eligible for, before you've finalized a property. For property investors, the question is whether pre-approval actually strengthens your negotiating position with the developer. The answer is yes — and here's why.
What pre-approval signals:
A pre-approval letter signals to the developer that you are a serious, qualified buyer with verified financial capacity. The bank has already assessed your income, credit score, and repayment capacity, and has committed (conditionally) to lending you a specific amount.
This matters to the developer because a significant percentage of property bookings fall through due to loan rejection — the buyer books the property but cannot secure the loan. A pre-approved buyer eliminates this risk, making them a more attractive prospect.
How it strengthens negotiation:
1. Credibility: The developer knows you can close the transaction, which gives you credibility in price negotiation. A pre-approved buyer is treated as a 'ready' buyer, not a 'prospective' buyer.
2. Faster closing: The loan sanction process is already done, so the transaction can close faster. Developers value faster closing (it means faster cash flow), and may offer a small discount in exchange.
3. Leverage in bulk negotiation: If you're part of a syndicate, pre-approved buyers strengthen the syndicate's negotiating position. A syndicate of 10 pre-approved buyers is a more compelling proposition than 10 'interested' buyers.
The limitations:
1. Pre-approval is not final sanction: The pre-approval is conditional — it's subject to the property's valuation, legal clearance, and the bank's final underwriting. It doesn't guarantee the loan will be disbursed.
2. It doesn't change the property's fundamentals: Pre-approval strengthens your negotiating position, but it doesn't change the property's value or the market dynamics. The discount you can negotiate is still bounded by the developer's pricing strategy and the market conditions.
3. Validity period: Pre-approvals are typically valid for 3–6 months. If you don't finalize a property within that period, you'll need to reapply.
How to get pre-approved:
1. Submit your income documents (salary slips, tax returns, bank statements) to 2–3 banks or HFCs.
2. The bank assesses your eligibility and issues a conditional sanction letter stating the loan amount, rate, and tenure.
3. The letter is valid for 3–6 months, during which you can finalize a property.
4. Once you finalize a property, the bank does the property valuation and legal due diligence, and issues the final sanction.
Our advice: get pre-approved before you start property hunting. It costs nothing (banks don't charge for pre-approval), it signals seriousness, and it strengthens your negotiating position. Even if you plan to self-fund, a pre-approval gives you a fallback option and a negotiating tool. The pre-approval is not a commitment to take the loan — it's a signal of your financial capacity.
Want these insights delivered before anyone else?
Join our confidential investor briefing — subvention alerts, off-market deals and market intelligence, first.
More from Investment Strategy
How Investor Syndication Unlocks Wholesale Developer Pricing
One investor gets retail pricing. Ten investors syndicated through us get wholesale. Here's the mechanics of bulk-buying power.
REITs vs Physical Property: Where Should the Smart Money Go?
Indian REITs offer liquidity and yield, but physical property offers leverage and appreciation. We compare the two.
How Indian Family Offices Are Allocating to Real Estate in 2026
Family offices are shifting from pure equity to real estate for yield, inflation hedge, and generational wealth. We break down the allocation framework.