Leverage in Real Estate: How Much Debt Is Optimal?
Debt amplifies returns but also risk. We analyze the optimal loan-to-value ratio for different investor profiles and market conditions.
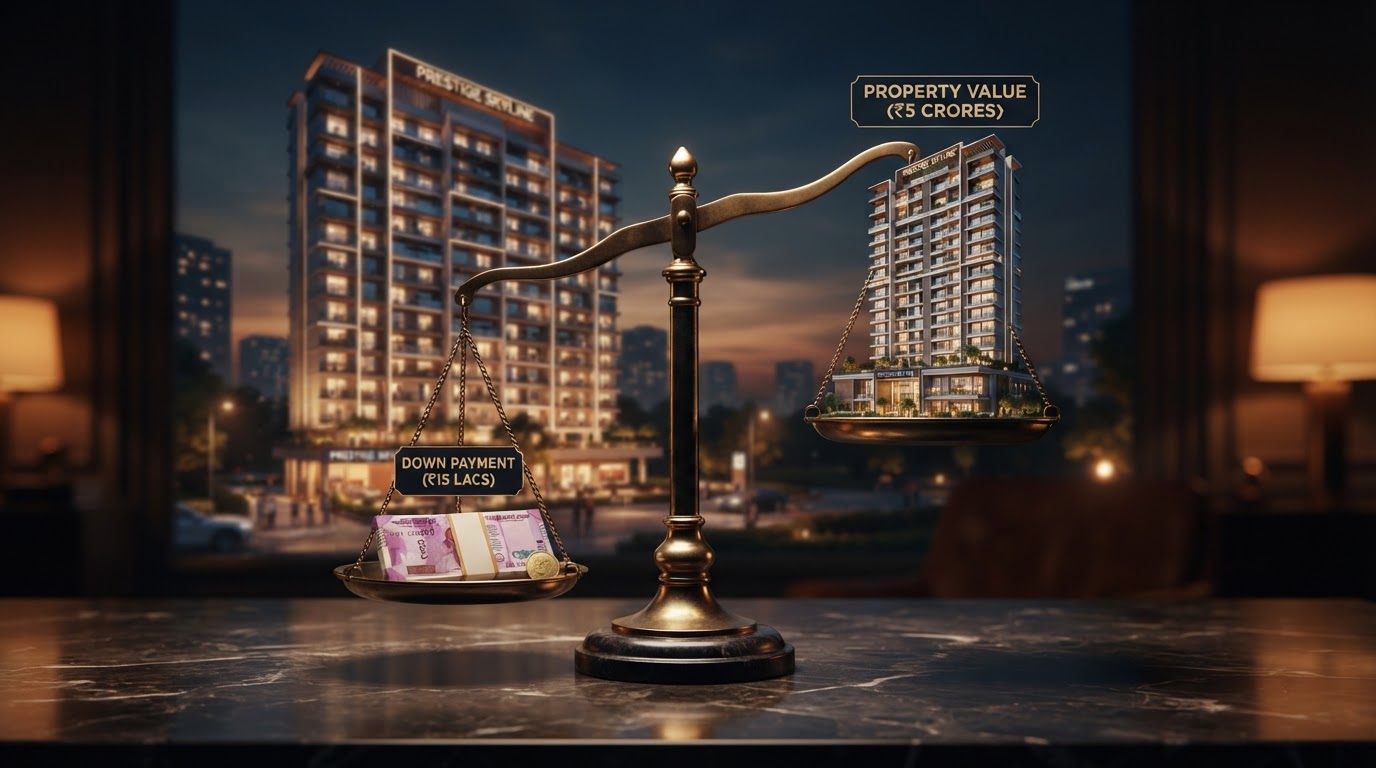
Leverage — the use of debt to amplify returns — is the most powerful and the most dangerous tool in real estate investing. Used well, it multiplies your ROI on invested capital. Used poorly, it can wipe out your equity in a downturn. Here's our framework for optimal leverage.
How leverage amplifies returns:
On a ₹2 Cr property with 25% appreciation: - Unleveraged (100% equity): ₹2 Cr entry, ₹2.5 Cr exit. Gain = ₹50 lakh. ROI = 25%. - 20% down, 80% loan (subvention): ₹40 lakh entry, ₹2.5 Cr exit. Gain = ₹50 lakh (minus loan principal of ₹1.6 Cr, which is paid at possession). ROI on invested capital = 125%.
The leverage multiplies the ROI on invested capital because the appreciation accrues on the full property value, while your capital at risk is only the down payment.
The risk of leverage:
The same amplification works in reverse. If the property depreciates 10%: - Unleveraged: ₹2 Cr entry, ₹1.8 Cr exit. Loss = ₹20 lakh. ROI = -10%. - 20% down, 80% loan: ₹40 lakh entry, ₹1.8 Cr exit. Loss = ₹20 lakh + you still owe ₹1.6 Cr. Your equity is wiped out. ROI = -50%.
The optimal LTV (loan-to-value) ratio:
The optimal leverage depends on the investor's risk profile, the property's appreciation outlook, and the interest rate environment.
- Conservative (30–40% LTV): Suitable for stability-focused investors and high-priced markets (Mumbai luxury) where appreciation is moderate. The lower leverage provides downside protection. - Moderate (50–60% LTV): The sweet spot for most investors. Enough leverage to amplify returns, but enough equity to absorb a 10–15% correction. - Aggressive (70–80% LTV): Suitable for high-conviction appreciation plays in emerging markets, where the appreciation outlook is strong (20%+). The higher leverage maximizes ROI but requires confidence in the appreciation thesis.
The subvention advantage:
Subvention is a unique form of leverage that eliminates the interest cost during construction. With a 20:80 subvention, you get 80% leverage at zero interest cost — the builder carries the balance. This is the most capital-efficient form of leverage available, and it's why subvention (when available on tier-1 projects) is so powerful.
The rate environment matters:
The interest rate on the loan determines whether leverage is accretive or dilutive. If the property's total return (appreciation + yield) exceeds the loan interest rate, leverage is accretive. If the return is below the interest rate, leverage is dilutive.
In the current environment (home loan rates at 8.5–9.5%, residential appreciation at 12–18%), leverage is accretive for well-selected properties. But the margin is not wide — a slowdown in appreciation could make leverage dilutive.
Our framework: Use leverage, but use it judiciously. For most investors, a 50–60% LTV on under-construction property (via CLP or subvention) is the optimal balance of return amplification and risk management. Avoid over-leveraging (>80% LTV) unless you have high conviction in the appreciation thesis and the financial capacity to absorb a correction.
Want these insights delivered before anyone else?
Join our confidential investor briefing — subvention alerts, off-market deals and market intelligence, first.
More from Investment Strategy
How Investor Syndication Unlocks Wholesale Developer Pricing
One investor gets retail pricing. Ten investors syndicated through us get wholesale. Here's the mechanics of bulk-buying power.
REITs vs Physical Property: Where Should the Smart Money Go?
Indian REITs offer liquidity and yield, but physical property offers leverage and appreciation. We compare the two.
How Indian Family Offices Are Allocating to Real Estate in 2026
Family offices are shifting from pure equity to real estate for yield, inflation hedge, and generational wealth. We break down the allocation framework.