Tax-Loss Harvesting in Real Estate: Does It Apply?
Tax-loss harvesting is common in stocks. But does it work for real estate? We analyze the applicability and the set-off rules.
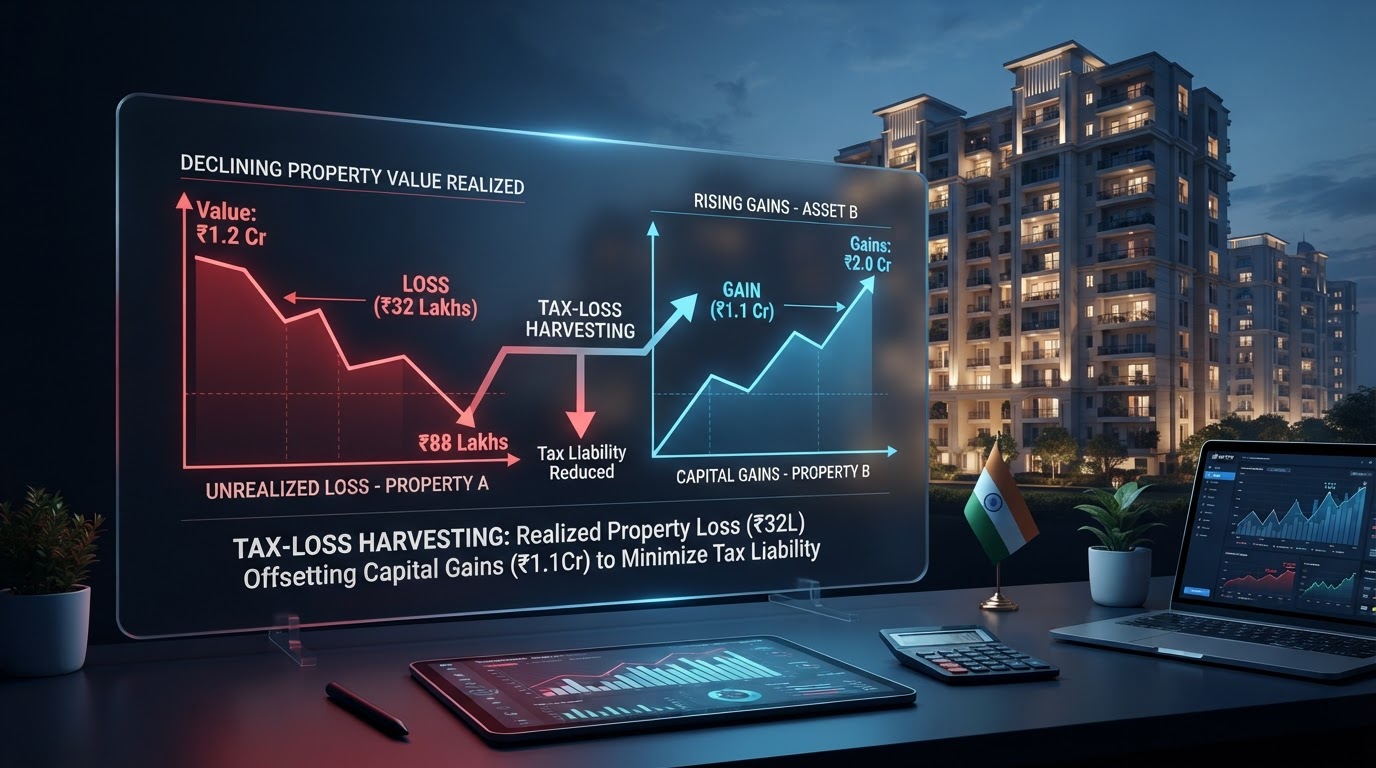
Tax-loss harvesting — selling an asset at a loss to offset gains on another asset — is a well-known strategy in equity investing. But does it apply to real estate? The answer is yes, but with important limitations that make it less practical than in equities. Here's the analysis.
The concept:
Tax-loss harvesting involves selling an asset that has declined in value, realizing the capital loss, and using that loss to offset capital gains on other assets. This reduces the overall tax liability.
In equities, this is straightforward — you sell a losing stock, book the loss, and offset it against gains on winning stocks. The transaction is quick, liquid, and low-cost.
In real estate, the concept applies but with significant practical constraints:
1. Set-off rules: Under Indian income tax law, capital losses can be set off against capital gains, but with specific rules: - Short-term capital loss (STCL) can be set off against both short-term and long-term capital gains. - Long-term capital loss (LTCL) can only be set off against long-term capital gains. - Capital losses cannot be set off against other income (salary, business income, etc.).
2. Same-head requirement: The loss and the gain must both be capital gains. You cannot offset a real estate capital loss against salary income or business income.
3. Same-year requirement: The set-off is within the same financial year. If the loss exceeds the gains in that year, the unabsorbed loss can be carried forward for 8 assessment years.
The practical challenges:
1. Illiquidity: Real estate is illiquid. Selling a property at a loss takes 6–12 months (finding a buyer, negotiating, registering). By the time the sale is complete, the tax year may have changed, and the set-off opportunity may be lost.
2. Transaction cost: Selling real estate involves significant transaction costs — brokerage (if any), legal fees, stamp duty on the buyer's side (which reduces the net sale price). These costs erode the tax benefit.
3. Limited loss scenarios: Real estate generally appreciates over time. A property sold at a loss is relatively rare — it typically happens only when the property was purchased at a peak, the micro-market declined, or the property has defects (title, construction, legal). Most investors don't have loss-making real estate to harvest.
4. Small loss amounts: Even when a property is sold at a loss, the loss amount is typically small relative to the investor's total portfolio. The tax saving from offsetting a small loss is modest.
When it does apply:
Tax-loss harvesting in real estate is most relevant in these scenarios:
1. Offsetting a large gain: If you have a large capital gain from selling a profitable property, and you also hold a loss-making property, selling the loss-making property in the same year can offset the gain and reduce the tax.
2. Commercial property losses: Commercial property can see sharper declines (particularly in downturns or when a tenant vacates). A commercial property loss can offset gains on residential property (both are capital gains).
3. Under-construction assignment losses: If you assigned an under-construction property at a loss (the assignment price was below your total payment), the loss can offset gains on other properties.
The alternative — Section 54 and 54EC:
For most investors, the more practical tax-saving strategy is not loss harvesting but exemption under Section 54 (reinvesting the gain in another residential property) or Section 54EC (investing in 54EC bonds). These exemptions eliminate the capital gains tax entirely, which is more valuable than offsetting a loss.
Our view: tax-loss harvesting in real estate is theoretically applicable but practically limited. The illiquidity, transaction costs, and rarity of real estate losses make it a less useful strategy than in equities. For most investors, the focus should be on exemption (Section 54/54EC) rather than loss harvesting. If you do have a loss-making property and a large gain in the same year, consult a CA to evaluate the set-off — but don't hold a loss-making property solely for the tax-loss harvesting benefit.
Want these insights delivered before anyone else?
Join our confidential investor briefing — subvention alerts, off-market deals and market intelligence, first.
More from Investment Strategy
How Investor Syndication Unlocks Wholesale Developer Pricing
One investor gets retail pricing. Ten investors syndicated through us get wholesale. Here's the mechanics of bulk-buying power.
REITs vs Physical Property: Where Should the Smart Money Go?
Indian REITs offer liquidity and yield, but physical property offers leverage and appreciation. We compare the two.
How Indian Family Offices Are Allocating to Real Estate in 2026
Family offices are shifting from pure equity to real estate for yield, inflation hedge, and generational wealth. We break down the allocation framework.