NRE vs NRO Account: Which to Use for Property Purchase?
The account you use to fund your property purchase affects repatriation, taxation, and flexibility. We compare NRE and NRO for property investment.
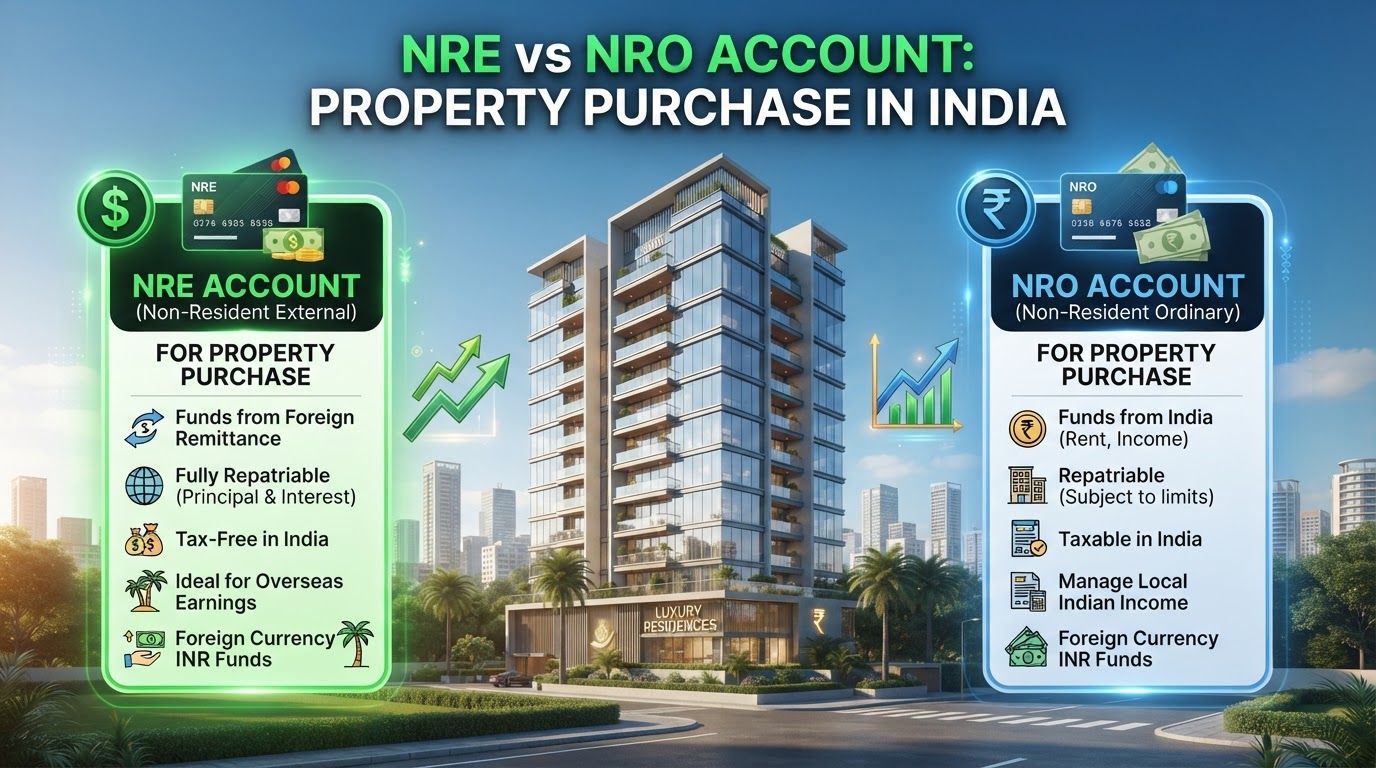
The choice between NRE (Non-Resident External) and NRO (Non-Resident Ordinary) accounts for funding a property purchase has significant implications for repatriation, taxation, and flexibility. Here's the comparison.
NRE account:
An NRE account is used to hold foreign currency remitted to India. The funds in an NRE account are freely repatriable (can be transferred abroad without limit). The account is maintained in INR (the foreign currency is converted to INR on deposit).
Key features for property purchase: - Funding: You remit foreign currency from your overseas account to the NRE account, which is converted to INR. You then use the INR to pay the developer. - Repatriation: The principal amount (the original purchase price funded by NRE) can be repatriated immediately upon sale, without limit. The capital gain is subject to the USD 1 million annual limit. - Taxation: The interest earned on the NRE account is tax-free in India. The capital gains on the property are taxed as per NRI capital gains rules. - Flexibility: High. The funds are freely repatriable, and the principal is not locked in.
NRO account:
An NRO account is used to hold Indian-source income — rent, dividends, pension, salary earned before becoming NRI, and sale proceeds of property. The funds in an NRO account are repatriable up to USD 1 million per financial year.
Key features for property purchase: - Funding: You can use Indian-source income (rent, savings) in the NRO account to fund the property purchase. You can also remit foreign currency to the NRO account, but it loses the 'freely repatriable' status. - Repatriation: Sale proceeds must be credited to the NRO account. Repatriation is limited to USD 1 million per financial year, including all current income and capital transactions. - Taxation: The interest earned on the NRO account is taxable in India (at the NRI's slab rate, with TDS at 30%+cess). The capital gains on the property are taxed as per NRI capital gains rules. - Flexibility: Lower. The repatriation is limited, and the funds are less freely transferable.
Which to use for property purchase?
For most NRI investors, the NRE account is the preferred funding source:
1. Repatriation advantage: The principal (original purchase price) is freely repatriable from NRE-funded property. This means when you sell, you can move the original investment back abroad without limit. Only the gain is subject to the USD 1 million limit.
2. Tax-free interest: Any funds held in the NRE account before the property purchase (or after the sale) earn tax-free interest.
3. Cleaner compliance: NRE-funded transactions have simpler repatriation documentation (the source of funds is clearly foreign currency).
When to use NRO:
The NRO account is appropriate when: - You have Indian-source income (rent from existing property, dividends, pension) that you want to deploy for a new property purchase. - You're selling an existing property and want to reinvest the proceeds in a new property (the sale proceeds must go to NRO first, then can be used for the new purchase). - You want to keep the funds in India for ongoing expenses (maintenance, family support) rather than repatriating.
The hybrid approach:
Many NRI investors use a hybrid approach: fund the property purchase with NRE funds (for the repatriation advantage), and use the NRO account for Indian-source income and ongoing property-related expenses (maintenance, property tax, society dues).
Our advice: for property investment, fund the purchase with NRE funds. The repatriation advantage is significant — it means your principal is freely movable, which is important if you plan to eventually sell and move the proceeds abroad. Use the NRO account for Indian-source income and ongoing expenses, but don't use it to fund the property purchase unless you have no foreign currency to remit.
Want these insights delivered before anyone else?
Join our confidential investor briefing — subvention alerts, off-market deals and market intelligence, first.
More from NRI Investing
NRI Investors Are Quietly Buying Bengaluru Again — Here's Why
Rupee depreciation, RERA maturity and tech-corridor yield are pulling Gulf and Singapore-based NRIs back into Bengaluru.
NRI Real Estate Investment: The Complete FEMA Compliance Guide
NRI property investment in India requires specific FEMA compliance. We cover the rules, accounts, repatriation, and tax implications.
NRI Property Taxation: The Complete Guide
NRI property taxation is complex — TDS, capital gains, surcharge, and repatriation rules all apply. Here's the complete framework.