NRI Home Loans in India: Eligibility, Process, and Documentation
NRIs can get home loans in India, but the eligibility and documentation differ from residents. We explain the process and the key requirements.
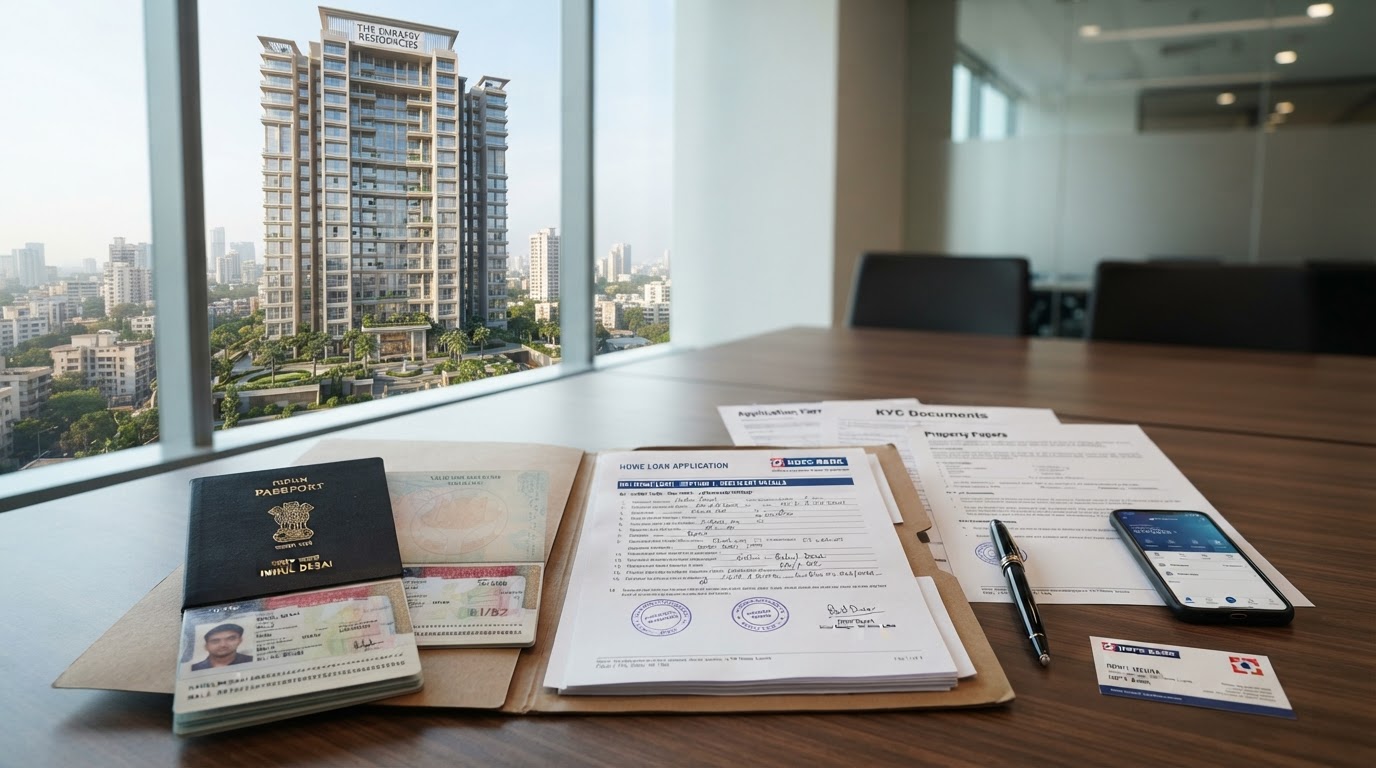
NRIs can obtain home loans from Indian banks and housing finance companies to purchase property in India. The loan structure is similar to resident home loans, but the eligibility criteria, documentation, and disbursement process have NRI-specific requirements. Here's the guide.
1. Eligibility criteria:
- Age: 21–60 years (some banks extend to 65 for professionals). - Employment: Salaried or self-employed, with a minimum overseas income threshold (typically USD 3,000–5,000 per month, varying by bank). - Country of residence: Most Indian banks have an approved list of countries from which they accept NRI loan applications. Gulf countries, USA, UK, Singapore, and Australia are universally accepted; some African and Central Asian countries may not be on the list. - Credit history: The bank assesses the NRI's overseas credit history (if available) and Indian credit history (CIBIL score, if the NRI has existing Indian credit). - Power of Attorney (POA): The NRI must appoint a POA holder in India (usually a family member) to execute documents and interact with the bank and the developer on their behalf.
2. Loan amount and LTV:
The loan amount is determined by the property value and the NRI's income: - LTV: Up to 80% of the property value (same as residents). - Income multiplier: The EMI is typically capped at 40–50% of the NRI's monthly income (net of overseas obligations). - Loan tenure: Up to 30 years (some banks cap at 20 years for NRIs).
3. Interest rates:
NRI home loan interest rates are typically 0.25–0.50% higher than resident home loan rates. This is because banks perceive a slightly higher risk on NRI loans (repatriation risk, legal recourse complexity). Current NRI home loan rates are in the 8.75–10% range.
4. Documentation:
- Passport copy and visa/residence permit - Overseas employment proof (employment letter, salary slips for 6 months) - Overseas bank statements (6 months) - NRE/NRO account statements - PAN card - Power of Attorney (notarized and attested by the Indian consulate in the resident country) - Property documents (sale agreement, RERA registration, approvals) - Credit report (if available from the resident country)
5. The POA (Power of Attorney):
The POA is a critical document for NRI home loans. Since the NRI is not physically present in India, the POA holder (usually a parent, spouse, or sibling) is authorized to sign loan documents, execute the sale agreement, and interact with the bank and the developer.
The POA must be: - Drafted on stamp paper in India (or printed and notarized abroad) - Notarized in the resident country - Attested by the Indian consulate/embassy in the resident country - Adjudicated by the local sub-registrar in India (within 3 months of arrival)
The POA is specific to the property transaction — it's not a general POA. It authorizes the POA holder only for the specific property purchase and loan.
6. Disbursement:
For under-construction property, the loan is disbursed in installments tied to construction milestones (CLP), directly to the developer's account. The NRI pays pre-EMI (interest only on the disbursed amount) until full disbursement, after which the full EMI begins.
For ready-to-move property, the loan is disbursed in full at the time of registration.
7. Repayment:
The EMI is paid from the NRE/NRO account via direct debit or post-dated cheques. The NRI must remit funds to the NRE account (or maintain sufficient balance in the NRO account) to service the EMI.
8. Tax benefits:
NRIs can claim the same home loan tax benefits as residents: - Section 80C: Principal repayment up to ₹1.5 lakh per year (deduction from taxable income). - Section 24(b): Interest repayment up to ₹2 lakh per year on self-occupied property.
These deductions are available only if the NRI files an income tax return in India.
Our advice: NRI home loans are straightforward if the documentation is in order. The key is the POA — get it drafted, notarized, and attested early in the process, as it takes 4–6 weeks. Use a bank that has a dedicated NRI desk (SBI, HDFC, ICICI, Axis all have strong NRI home loan divisions). And fund the EMI through the NRE account, so the repayment is from freely repatriable funds.
Want these insights delivered before anyone else?
Join our confidential investor briefing — subvention alerts, off-market deals and market intelligence, first.
More from NRI Investing
NRI Investors Are Quietly Buying Bengaluru Again — Here's Why
Rupee depreciation, RERA maturity and tech-corridor yield are pulling Gulf and Singapore-based NRIs back into Bengaluru.
NRI Real Estate Investment: The Complete FEMA Compliance Guide
NRI property investment in India requires specific FEMA compliance. We cover the rules, accounts, repatriation, and tax implications.
NRI Property Taxation: The Complete Guide
NRI property taxation is complex — TDS, capital gains, surcharge, and repatriation rules all apply. Here's the complete framework.