NRI Repatriation Rules: How to Move Sale Proceeds Abroad
Repatriating property sale proceeds involves RBI limits, CA certificates, and bank procedures. We explain the step-by-step process.
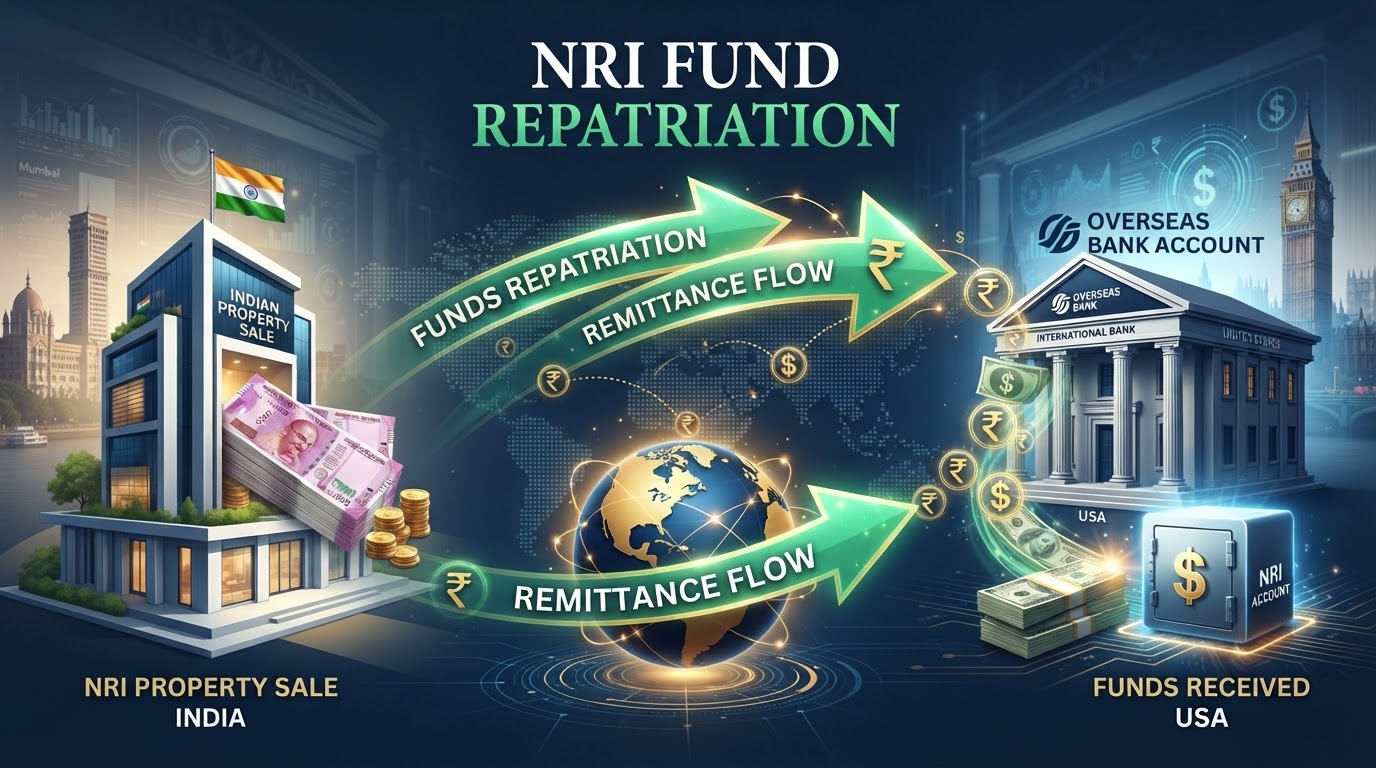
Repatriation — the process of moving property sale proceeds from India to the NRI's overseas account — is one of the most frequently asked questions from NRI investors. The rules are specific, and the process requires documentation. Here's the step-by-step guide.
1. Understand the repatriation limits:
The RBI's repatriation limits depend on how the property was funded:
- Property purchased with NRE/FCNR(B) funds (foreign currency remitted to India): The principal amount (up to the original purchase price) can be repatriated immediately upon sale, without any limit. The capital gain can also be repatriated, subject to the overall USD 1 million annual limit.
- Property purchased with NRO funds (Indian income, e.g., rent, salary earned in India before becoming NRI): Sale proceeds must be credited to the NRO account. Repatriation is limited to USD 1 million per financial year, including all current income and capital transactions.
- Inherited property: Sale proceeds can be repatriated up to USD 1 million per financial year, subject to the same documentation requirements.
2. Credit the sale proceeds to the NRO account:
The sale proceeds must first be credited to the NRO (Non-Resident Ordinary) account, even if the property was purchased with NRE funds. The NRO account is the designated account for all Indian-source income and sale proceeds.
3. Obtain CA certificates (Form 15CB and 15CA):
Before repatriating, the NRI must obtain: - Form 15CB: A certificate from a Chartered Accountant, confirming that the NRI's tax liabilities on the sale have been met. The CA verifies the capital gains calculation, the TDS, and the exemptions claimed. - Form 15CA: A declaration filed by the NRI (or the CA on their behalf) with the income tax department, based on the Form 15CB certificate. This is an online filing on the income tax portal.
The bank will not process the repatriation without these forms.
4. Submit repatriation request to the bank:
With the Form 15CB and 15CA in hand, the NRI submits a repatriation request to the bank where the NRO account is held. The bank verifies the forms, confirms the repatriation limit, and processes the transfer to the NRI's overseas account.
5. Timeline:
The entire repatriation process — from sale to funds reaching the overseas account — typically takes 4–8 weeks, depending on the CA's processing time, the bank's verification, and the RBI's approval (if required for amounts above the standard limit).
6. Documentation checklist:
- Sale deed and registration documents - PAN card - NRO account details - Form 15CB (CA certificate) - Form 15CA (filed declaration) - Bank's repatriation request form - Source of funds proof (NRE remittance certificates, if applicable)
7. Common pitfalls:
- TDS shortfall: If the buyer deducted less TDS than the actual tax liability, the NRI must pay the balance before repatriation. The CA will identify this in Form 15CB. - Exemption claims: If the NRI claims Section 54 or 54EC exemption, the reinvestment must be completed before repatriation. The CA verifies the reinvestment. - PAN not linked: The NRI's PAN must be linked to the NRO account and active on the income tax portal.
Our advice: start the repatriation process early. Engage the CA as soon as the sale is registered, so the Form 15CB/15CA can be prepared while the sale proceeds are being credited to the NRO account. This minimizes the delay between sale and repatriation. And always use NRE funds for property purchases — it makes the principal repatriation unlimited and simplifies the process.
Want these insights delivered before anyone else?
Join our confidential investor briefing — subvention alerts, off-market deals and market intelligence, first.
More from NRI Investing
NRI Investors Are Quietly Buying Bengaluru Again — Here's Why
Rupee depreciation, RERA maturity and tech-corridor yield are pulling Gulf and Singapore-based NRIs back into Bengaluru.
NRI Real Estate Investment: The Complete FEMA Compliance Guide
NRI property investment in India requires specific FEMA compliance. We cover the rules, accounts, repatriation, and tax implications.
NRI Property Taxation: The Complete Guide
NRI property taxation is complex — TDS, capital gains, surcharge, and repatriation rules all apply. Here's the complete framework.