NRI Real Estate: India vs Dubai vs Singapore — Where to Invest?
NRI investors often compare India, Dubai, and Singapore. We analyze the ROI, risk, and liquidity of each market for non-resident investors.
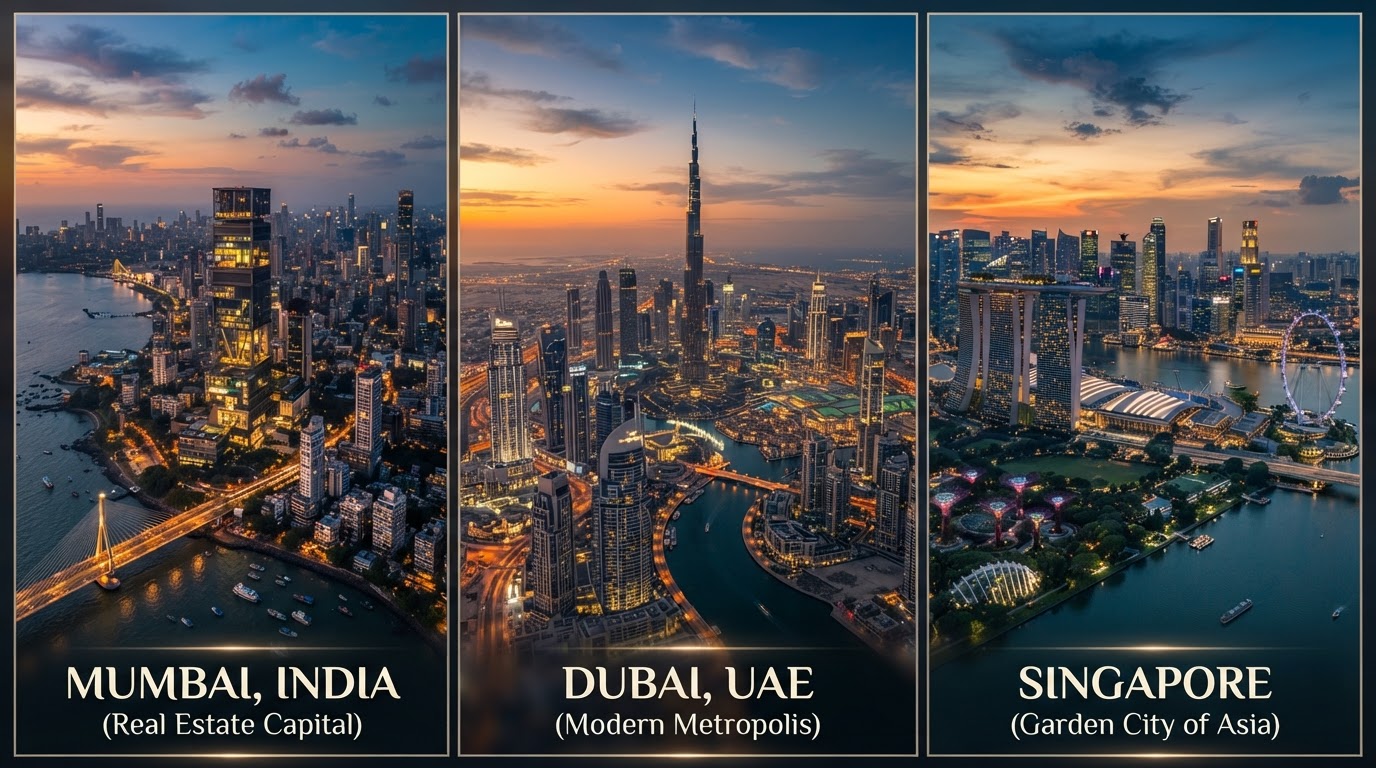
For NRI investors, the choice between Indian, Dubai, and Singapore real estate is a common dilemma. Each market offers a different risk-return-liquidity profile, and the optimal choice depends on the investor's objectives, risk appetite, and time horizon. Here's the comparison.
1. Entry pricing and ticket size:
India: - Premium residential (Bengaluru, Hyderabad): ₹1.5–3 Cr (USD 18,000–36,000) for a 3BHK. - Luxury residential (Mumbai): ₹5–15 Cr (USD 60,000–180,000). - The ticket size is lower than Dubai and Singapore, making it accessible for mid-ticket NRI investors.
Dubai: - Premium residential (Dubai Marina, Downtown): AED 1.5–3M (USD 400,000–800,000) for a 2BHK. - Luxury (Palm Jumeirah): AED 5–15M (USD 1.3–4M). - Higher ticket size than India, but lower than Singapore.
Singapore: - Premium residential (Orchard, Marina Bay): SGD 2–5M (USD 1.5–3.7M) for a 3BHK. - Additional Buyer's Stamp Duty (ABSD) for foreigners: 60% of property value (as of 2024). This makes Singapore the most expensive entry. - Very high ticket size, with the ABSD adding significant cost.
2. Appreciation potential:
India: - Pre-launch and under-construction residential in emerging corridors: 15–25% annual appreciation over 3–5 years. - The appreciation percentage is the highest of the three, driven by structural demand (IT employment, urbanization) and supply constraints in key micro-markets.
Dubai: - 5–10% annual appreciation in prime areas. The market has stabilized after the 2020–2023 surge, and appreciation is now moderate. - The risk of oversupply in certain segments (off-plan) is a concern.
Singapore: - 2–5% annual appreciation. The market is mature and stable, with limited upside due to the high entry pricing and the ABSD. - The total return (appreciation + yield) is modest.
3. Rental yield:
India: 2–4% (residential), 6–9% (commercial). Lower yield, but the appreciation compensates. Dubai: 5–8% (residential). Higher yield, attractive for income-focused investors. Singapore: 2–3% (residential). Low yield, consistent with the high entry pricing.
4. Liquidity:
India: Moderate. Resale takes 3–9 months, and the buyer pool is narrower for luxury inventory. Under-construction exits (assignment) are possible but have tax and transfer costs. Dubai: High. The market is liquid, with a active resale and off-plan transfer market. Resale typically takes 1–3 months. Singapore: High. The market is mature and liquid, with a well-regulated resale process. Resale takes 2–4 months.
5. Taxation:
India: Capital gains tax (12.5% LTCG, slab rate STCG), TDS on sale, no tax on NRE account interest. Rental income taxed at slab rate (with 30% standard deduction). Dubai: No income tax on rental income, no capital gains tax. The tax-free environment is a major advantage. Singapore: Property tax (annual), stamp duty on purchase (with ABSD for foreigners), no capital gains tax (property is not subject to CGT in Singapore). Rental income taxed at the owner's income tax rate.
6. Regulatory environment:
India: RERA provides buyer protection, but enforcement varies by state. Title risk and project delay risk are higher than in Dubai and Singapore. Dubai: DLD (Dubai Land Department) and RERA Dubai provide strong regulation. Escrow accounts are mandatory for off-plan. Title is clear and transfer is efficient. Singapore: The most regulated and transparent market. Clear title, efficient transfer, strong buyer protection.
7. The ROI comparison:
For a USD 200,000 investment over 5 years: - India (Bengaluru pre-launch): 20% annual appreciation + 3% yield (post-possession) = ~23% total annual return. Total 5-year return = ~115%. Tax (12.5% LTCG) reduces net to ~100%. - Dubai (Marina ready-to-move): 7% appreciation + 6% yield = 13% total annual return. Total 5-year return = ~65%. No tax. Net = 65%. - Singapore (Orchard ready-to-move): 3% appreciation + 2.5% yield = 5.5% total annual return. Total 5-year return = ~28%. Plus ABSD (60%) on entry, which is a massive upfront cost. Net return is negative or marginal after ABSD.
Our framework: - For appreciation-focused NRI investors: India offers the highest ROI, with the trade-off of higher risk (title, delay) and lower liquidity. - For yield-focused NRI investors: Dubai offers the best yield with tax-free income and high liquidity. - For stability-focused NRI investors: Singapore offers the lowest risk, but the ABSD makes the entry cost prohibitive for most.
The optimal approach for many NRI investors is a split: a core position in India (for appreciation) and a yield position in Dubai (for tax-free income and liquidity). This balances the high-return, higher-risk Indian market with the stable, liquid Dubai market.
Our view: for NRI investors with Indian origins and a long-term horizon, India offers the best risk-adjusted return. The appreciation potential is the highest, the ticket size is accessible, and the FEMA framework is straightforward. The key is to invest through a vetted advisory (to manage title and developer risk) and to use NRE funds for the repatriation advantage. Dubai is a strong complement for the yield and liquidity sleeve.
Want these insights delivered before anyone else?
Join our confidential investor briefing — subvention alerts, off-market deals and market intelligence, first.
More from NRI Investing
NRI Investors Are Quietly Buying Bengaluru Again — Here's Why
Rupee depreciation, RERA maturity and tech-corridor yield are pulling Gulf and Singapore-based NRIs back into Bengaluru.
NRI Real Estate Investment: The Complete FEMA Compliance Guide
NRI property investment in India requires specific FEMA compliance. We cover the rules, accounts, repatriation, and tax implications.
NRI Property Taxation: The Complete Guide
NRI property taxation is complex — TDS, capital gains, surcharge, and repatriation rules all apply. Here's the complete framework.