NRI vs OCI vs Resident: Property Rights Compared
NRI, OCI, and resident Indian property rights differ in important ways. We compare what each category can and cannot buy.
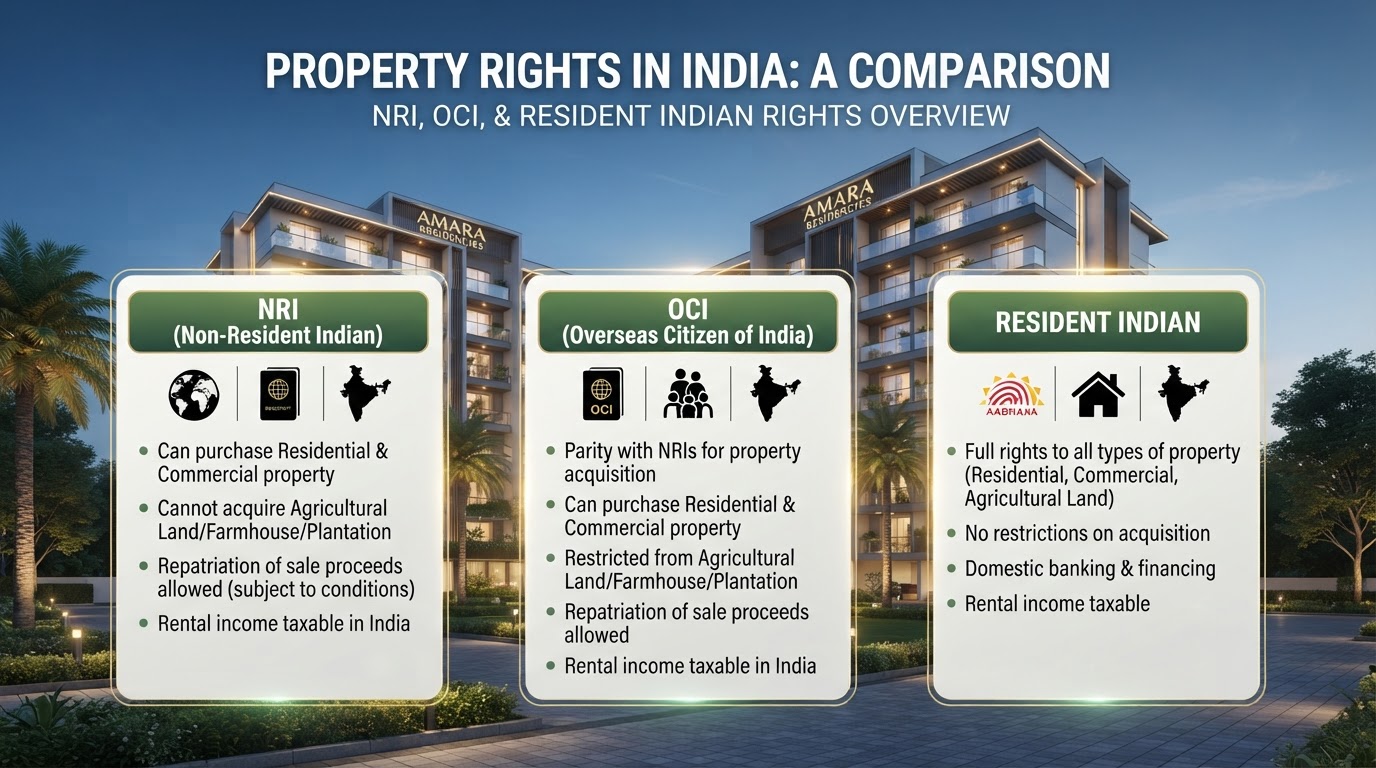
The property rights of NRIs, OCIs (Overseas Citizens of India), and resident Indians differ in important ways. Understanding these differences is essential for non-resident investors to ensure compliance and plan their investments correctly. Here's the comparison.
1. What each category can purchase:
Resident Indian: - Residential property (apartments, villas, houses): No restriction. - Commercial property (office, retail): No restriction. - Agricultural land, farmhouses, plantation property: No restriction. - Industrial land: No restriction.
NRI (Non-Resident Indian): - Residential property: No restriction (no upper limit on number of properties). - Commercial property: No restriction. - Agricultural land, farmhouses, plantation property: Cannot purchase. May inherit, but sale requires RBI permission.
OCI (Overseas Citizen of India): - Residential property: No restriction (same as NRI). - Commercial property: No restriction (same as NRI). - Agricultural land, farmhouses, plantation property: Cannot purchase (same as NRI).
2. The NRI-OCI parity:
Under FEMA regulations, OCIs are treated on par with NRIs for property purchase purposes. Both can buy residential and commercial property without RBI permission, and both are prohibited from buying agricultural land.
This parity was established to give OCIs (who hold foreign citizenship but have Indian origins) the same property rights as NRIs (who hold Indian citizenship but reside abroad).
3. Funding the purchase:
NRI and OCI: - Payment must be made through NRE/NRO/FCNR(B) accounts using foreign currency remitted from abroad, or funds already held in these accounts. - The payment cannot be made from a resident savings account or from Indian income that hasn't been credited to an NRO account.
Resident Indian: - Payment from any resident bank account, using any source of funds.
4. Repatriation of sale proceeds:
NRI and OCI: - NRE-funded property: Principal repatriable without limit; gain subject to USD 1 million annual limit. - NRO-funded property: Sale proceeds subject to USD 1 million annual repatriation limit. - Requires Form 15CB/15CA and CA certification.
Resident Indian: - No repatriation concept (the funds remain in India). If the resident later becomes an NRI, the existing property can be held and sold as NRI property, with repatriation subject to the rules above.
5. Taxation:
NRI and OCI: - Capital gains tax: Same rates as residents (LTCG 12.5% without indexation, STCG at slab rate). - TDS on sale: Higher TDS (12.5% for LTCG, slab rate for STCG) deducted by the buyer. - Tax benefits (Section 80C, 24b): Available if the NRI/OCI files an ITR in India.
Resident Indian: - Capital gains tax: Same rates. - TDS on sale: 0.1% (if sale value >₹50 lakh) — much lower than NRI TDS. - Tax benefits: Available with ITR filing.
6. The resident-to-NRI transition:
When a resident Indian becomes an NRI (due to moving abroad for employment), their existing property in India is not affected. They can continue to hold it, rent it, and sell it. The property is treated as NRI-held property from the date of status change, and future sales are subject to NRI taxation and repatriation rules.
The key consideration: the repatriation of sale proceeds is subject to the USD 1 million annual limit, regardless of when the property was purchased. So a resident who bought property and later becomes an NRI faces the same repatriation limit as an NRI who bought the property while non-resident.
7. Joint ownership:
NRIs and OCIs can jointly own property with: - Another NRI/OCI: No restriction. - A resident Indian: No restriction (the resident's share is not subject to NRI rules).
Joint ownership is useful for tax planning (the resident co-owner gets lower TDS on their share) and for repatriation (the resident co-owner's share is freely movable).
Our advice: understand your status (NRI, OCI, or resident) and the associated property rights before investing. The key restrictions are on agricultural land (prohibited for NRI/OCI) and on repatriation (limited for NRI/OCI). For residential and commercial property, NRIs and OCIs have the same rights as residents — the differences are in funding, taxation, and repatriation, not in the right to purchase.
Want these insights delivered before anyone else?
Join our confidential investor briefing — subvention alerts, off-market deals and market intelligence, first.
More from NRI Investing
NRI Investors Are Quietly Buying Bengaluru Again — Here's Why
Rupee depreciation, RERA maturity and tech-corridor yield are pulling Gulf and Singapore-based NRIs back into Bengaluru.
NRI Real Estate Investment: The Complete FEMA Compliance Guide
NRI property investment in India requires specific FEMA compliance. We cover the rules, accounts, repatriation, and tax implications.
NRI Property Taxation: The Complete Guide
NRI property taxation is complex — TDS, capital gains, surcharge, and repatriation rules all apply. Here's the complete framework.