Co-Living Spaces: The Affordable Urban Model
Co-living is reshaping urban rental housing for young professionals. We analyze the investment profile and whether it's a sustainable yield play.
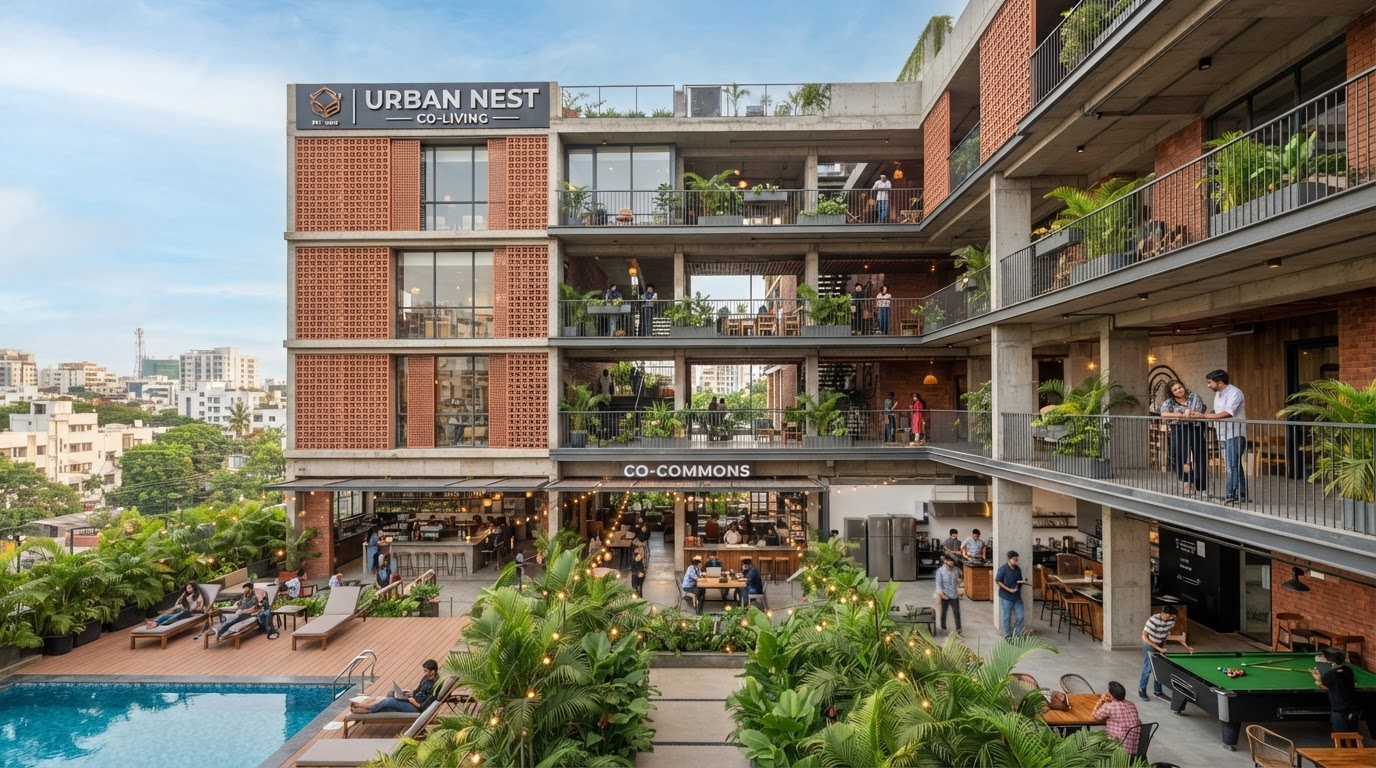
Co-living — shared, managed residential spaces designed for young professionals and students — has emerged as a distinct real estate segment, addressing the affordable urban rental housing gap. For investors, co-living offers a higher yield than traditional residential rental, but with higher operating complexity and tenant turnover.
The co-living model:
Co-living spaces are professionally managed shared residential units, where residents rent a private bedroom (or a shared bedroom) and share common areas (kitchen, living, dining, laundry). The model includes:
1. Furnished units: The units are fully furnished and equipped, reducing the resident's setup cost.
2. Managed services: Housekeeping, maintenance, Wi-Fi, and utilities are included in the rent, providing a hassle-free experience.
3. Community: Co-living emphasizes community — common areas, events, and a curated resident mix create a social environment.
4. Flexible tenure: Leases are typically 3–12 months, providing flexibility for young professionals who may relocate.
The demand drivers:
1. Young professionals: The primary demographic is young professionals (22–30 years) in IT and corporate hubs, who value affordability, flexibility, and community over space and privacy.
2. Students: Post-graduate and working students in education hubs (Bangalore, Pune, Delhi) who need affordable, managed housing.
3. Migration: Young professionals migrating to tier-1 cities for work, who need short-term, hassle-free housing before settling into a long-term rental or purchase.
The market:
The co-living market in India is growing rapidly, with approximately 100,000 beds across all operators. The key operators: Stanza Living, Colive, Zolo, Nestaway, and co-working operators extending into co-living (WeWork, Awfis).
The key markets are the IT and education hubs: - Bengaluru (ORR, Whitefield, Electronic City, Sarjapur) - Pune (Hinjewadi, Baner, Viman Nagar) - NCR (Gurgaon, Noida) - Hyderabad (HITEC City, Financial District) - Chennai (OMR)
The investment profile:
1. Higher yield: Co-living yields are 6–9% (on a managed basis), significantly higher than traditional residential rental (2–4%). The higher yield reflects the higher rent per sq ft (shared units generate more rent per sq ft than individual units) and the managed services premium.
2. Higher operating cost: The managed services (housekeeping, maintenance, Wi-Fi, community management) increase the operating cost, reducing the net yield. The net yield (after operating cost) is 4–6%.
3. Higher tenant turnover: The flexible tenure (3–12 months) creates higher tenant turnover, with vacancy risk and re-leasing cost. The occupancy must be maintained at 85%+ for the yield to be attractive.
4. Capital appreciation: Co-living properties appreciate at the standard residential rate (10–15% annually), as the underlying asset is residential real estate.
The investment routes:
1. Direct investment: Buy residential units and lease them to a co-living operator (Stanza, Zolo) on a revenue-share or fixed-rent model. The operator manages the units, and the investor earns the yield. Ticket size: ₹50 lakh–2 Cr.
2. Operator equity: Invest in co-living operators via private equity or pre-IPO rounds, for exposure to the segment's growth.
3. Fractional ownership: Some platforms offer fractional ownership of co-living portfolios, with professional management.
The risks:
1. Operating risk: The co-living yield depends on the operator's management quality — occupancy, rent collection, cost control. A poorly managed co-living property will have low occupancy and low yield.
2. Regulatory: Co-living is not a formally regulated segment. Some municipalities have raised concerns about shared housing (safety, zoning). Regulatory changes could impact the operating model.
3. Tenant turnover: The high tenant turnover creates vacancy risk. In a downturn (job losses, migration reversal), occupancy could drop sharply.
4. Competition: The co-living market is competitive, with multiple operators in the same micro-markets. Over-supply in a micro-market could pressure rents and occupancy.
Our view: co-living is a legitimate higher-yield residential investment, but it requires active management (directly or via an operator) and carries higher operating and turnover risk. For investors seeking higher yield from residential real estate, co-living (via a reputable operator on a revenue-share model) offers a 4–6% net yield, higher than traditional rental. The key is selecting the right operator (with a strong track record) and the right micro-market (IT/education hubs with strong young-professional demand). Co-living is best suited as a yield diversifier within a residential portfolio, not as a core holding.
Want these insights delivered before anyone else?
Join our confidential investor briefing — subvention alerts, off-market deals and market intelligence, first.
More from Sustainable & Future Trends
Green Building Certification (IGBC/GRIHA): The Premium Driver
IGBC and GRIHA certified buildings command a 5–10% pricing premium and higher rental yields. We analyze the green building investment case.
EV Charging in Residential Complexes: The New Amenity
EV charging is becoming a must-have amenity in premium residential complexes. We analyze the impact on property value and the investment case.
Senior Living Communities: The Demographic-Driven Segment
India's senior population is growing rapidly, creating demand for dedicated senior living communities. We analyze the investment opportunity.